The retirement account (Altersvorsorgedepot) has already been decided. Now the legislative process for a further subsidy component is also getting under way: the early start pension (Frühstartrente). 5 questions and answers about the plans.
What is the goal?
With the early start pension, every child in Germany is to receive start-up capital for their own retirement provision. It is also meant as an incentive to engage with the capital market early on, and to see, for example, what investing can do for building wealth.
This is meant to encourage people to continue their private provision later. A seamless transition from the early start pension subsidy to the subsidy for the new retirement account is possible. Because making more private provision will be indispensable in future.
How does the early start pension work?
From the age of six until the age of 18, every child is to receive 10 euros per month from the state. The money is to go into an individual, funded retirement account that parents can open with a private provider of their choice.
Only certified standard accounts are subsidised. Special rules apply to them. For example, the effective costs may be no more than 1.0 percent. Charging acquisition and distribution costs is not allowed.
What if parents do not open an account for their children?
For all children whose parents do not set up an account, the state invests the money collectively on the capital market. The Deutsche Bundesbank is to manage it, investing the money in shares or equity funds and diversifying it worldwide.
At 18, the young adults can transfer the capital saved for them into their own retirement account and use the subsidy available for it. However, the money must be claimed by the age of 35 at the latest.
What does the early start pension bring?
The state subsidy adds up to 1,440 euros by the age of 18. Private top-ups, for example from parents and relatives, are possible up to 6,840 euros per year. This makes saving even more attractive, because the return opportunities can then unfold even more strongly. Income from the early start pension remains tax-free until the payout phase begins. It is taxed retrospectively.
Payout of the subsidised capital is planned from the age of 65 at the earliest. Example calculations clearly show the advantage of starting to save early and the power of compound interest.
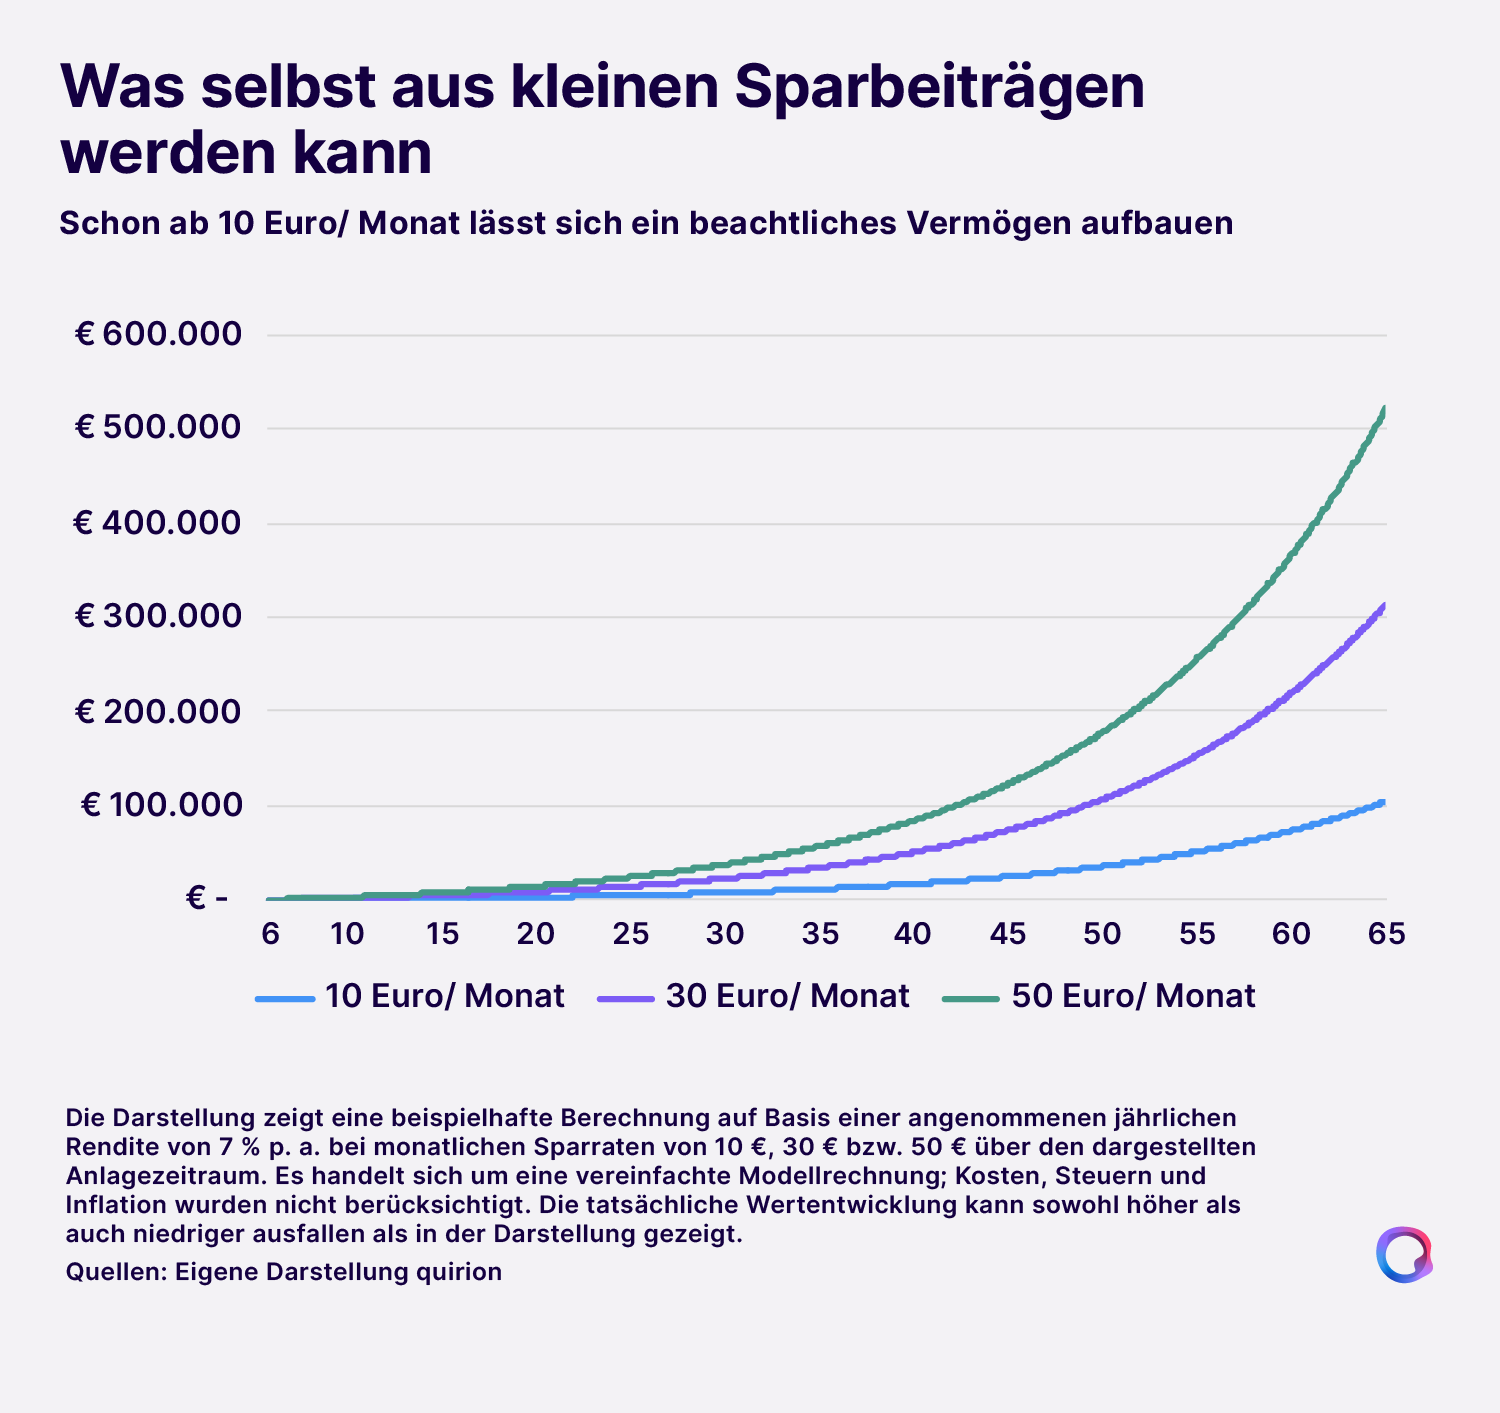
What the savings can become
The chart shows an example calculation based on an assumed annual return of 7% p.a. with monthly savings of €10, €30 or €50 over the investment period shown. It is a simplified model calculation; costs, taxes and inflation were not taken into account. The actual performance can be higher or lower than shown in the chart.
Even if only the state's contributions of 1,440 euros in total are paid in, an account value of around 53,000 euros at 65 is possible, according to an estimate by the Federal Ministry of Finance. As with all investments, there is no guarantee of this. The result can be better or worse.
What happens next?
The early start pension still has to go through the legislative process. This is to happen this year, so that the law can come into force on 1 January 2027. Children born in 2020 are to be the first year group and receive the subsidy retroactively. From 2027, each year the year group that has then turned six is to be added.
Will quirion offer an early start pension product?
Definitely. We are currently preparing our products for the new retirement account. A standard account is a mandatory part of this. Parents will be able to use it for their children's early start pension. One thing is already clear: we will stay well below the maximum cost cap of 1 percent, so that the retirement account and the early start pension really pay off.
You can find more information about the new retirement account here.