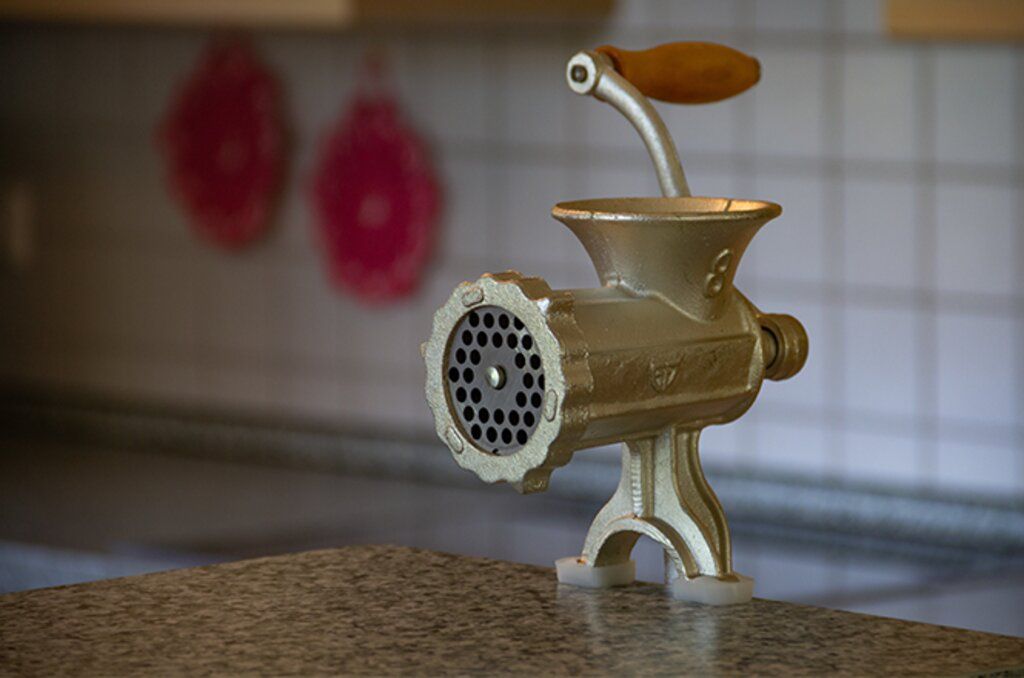
We recently came across a small piece of research on the news portal Finanz-Szene.de by financial journalist Christian Kirchner, who reports there on the sense and nonsense of selling certificates. By now this market has swelled in Germany to a volume of €70 billion. For background: the performance of certificates depends on the performance of other financial products. Like a meat grinder, banks break down the cash flows of existing standard stocks and bonds and blend the individual parts into new products for resale. The point of it all:
- A nice interest rate can be printed on the product, for example 10%. To the clueless investor, that sounds like a great deal. But the fact that this interest is in no way guaranteed and is only paid in certain market scenarios is often something the investor probably isn't aware of. Under certain conditions, often when things go badly, the certificate instead "flips" into equity mode and then passes the entire loss of the underlying stock through to the investor.
- It pays off for the bank, part I. With certificates, the costs are not transparent but are skimmed off by the bank in the course of the meat-grinder exercise. Anyone who digs into the fine print will find shocking costs of 2.9% or even 4.9% in the first year of the investment. For comparison: at quirion, €30,000 can be invested at total costs of 0.53% p.a. So anyone who buys a certificate pays a whopping 5 to 9 times more than with us, for ground beef instead of fillet steak.
- It pays off for the bank, part II. Yes, we did have to repeat it just the same: anyone who buys a certificate from a bank is lending the bank money that, in the event of insolvency, unlike an investment in classic funds or ETFs, is not protected. The bank can pass risks from securities held in its own portfolio on to the customer, use the customer's money for its own business, and on top of that still charges a hefty fee. Selling certificates therefore pays off not just twice, but even three times over.
- Certificates create a need for advice. Certificates have only a very limited shelf life and expire with regularity. The money that is freed up then has to be reinvested, with the adviser's help and at the costs already mentioned above.
The summary of the summary: certificates are opaque and harbor (and conceal) risks in more than one respect. By their very construction they cannot deliver attractive returns; instead they merely repackage the returns of the capital market, in exchange for a fee that is likely to eat up a large part of the capital market return. Certificates are therefore completely unsuitable for successfully building wealth. We consequently rule out their use for our clients' portfolios as a matter of principle.
P.S.: If you'd like to read the report cited above in the original, you'll find it here.